Flowers Foods reports low sales in Q3 2026
The performance reflects ongoing volume headwinds across the fresh packaged bread category as budget-conscious consumers adjusted purchasing habits.
USA – Flowers Foods, Inc. has reported a decline in sales and profitability for the third quarter of 2026, reflecting weaker product volumes, increased marketing expenditure, higher logistics costs and changing consumer purchasing behaviour.
The company recorded net sales of US$1.169 billion for the 12 weeks ended 10 October 2026, representing a 4.7% decrease compared with the corresponding period in 2025.
Net income declined by 63.6% to US$14.4 million, equivalent to 1.2% of sales.
Adjusted net income also fell by 56% to US$21.4 million, while adjusted earnings before interest, taxes, depreciation and amortization (EBITDA) decreased by 33.2% to US$78.9 million.
Adjusted EBITDA represented 6.8% of net sales, down 280 basis points year-on-year.
Diluted earnings per share (EPS) decreased by US$0.12 to US$0.07, while adjusted diluted EPS declined by US$0.13 to US$0.10.
According to the company, favourable price and product mix were insufficient to offset lower sales volumes during the quarter.
Chairman and Chief Executive Officer Ryals McMullian said the results reflected continued pressure on household budgets, evolving consumer preferences and heightened promotional activity across the bakery sector.
He acknowledged that some of the company’s initiatives to stabilize performance were progressing more slowly than anticipated.
The company highlighted encouraging developments in its Nature’s Own bread brand following its relaunch with fewer and simpler ingredients.
However, improvements have been slower than expected, particularly in the packaged loaf category, where market conditions remain challenging.
The company has therefore revised its full-year 2026 financial outlook.
Flowers Foods now expects net sales of between US$5.016 billion and US$5.063 billion, compared with its previous forecast of US$5.070 billion to US$5.142 billion.
Adjusted EBITDA is projected to range between US$415 million and US$430 million, down from the earlier estimate of US$453 million to US$481 million.
Adjusted diluted EPS is expected to reach between US$0.63 and US$0.68, compared with the previous guidance of US$0.75 to US$0.85.
Operationally, branded retail sales declined by 5.1% to US$772.1 million, with volumes falling 8.6%. Other sales, including foodservice and store-brand products, decreased by 4% to US$397 million.
Growth in foodservice sales and favourable pricing partially offset weaker demand in other product categories.
McMullian said the company was accelerating initiatives to improve customer execution, address innovation gaps and align its product portfolio with changing consumer preferences.
Flowers Foods expects market conditions to remain challenging in the near term but remains confident in the long-term opportunities across fresh packaged bread, cakes, better-for-you snacks and foodservice.
Headquartered in Thomasville, Georgia, Flowers Foods is one of the largest packaged bakery manufacturers in the United States.
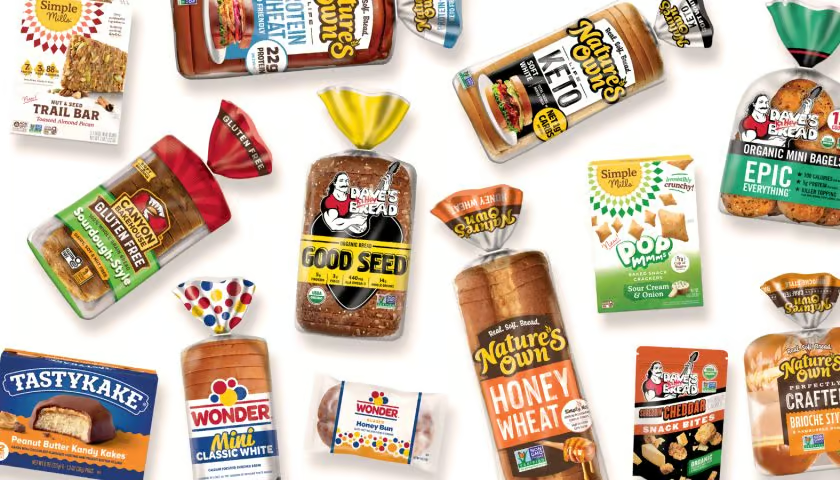
Its portfolio includes Nature’s Own, Dave’s Killer Bread, Canyon Bakehouse, Simple Mills, Wonder and Tastykake.
The latest results highlight the challenges facing the bakery sector as manufacturers respond to changing consumption patterns, promotional competition and rising operating costs.
Sign up to HERE receive our email newsletters with the latest news and insights from Africa and around the world, and follow us on our WhatsApp channel for updates.